· Press Release
Laba PTBA Melonjak Tiga Kali Lipat, capai Rp4,41 triliun hingga Triwulan III 2026
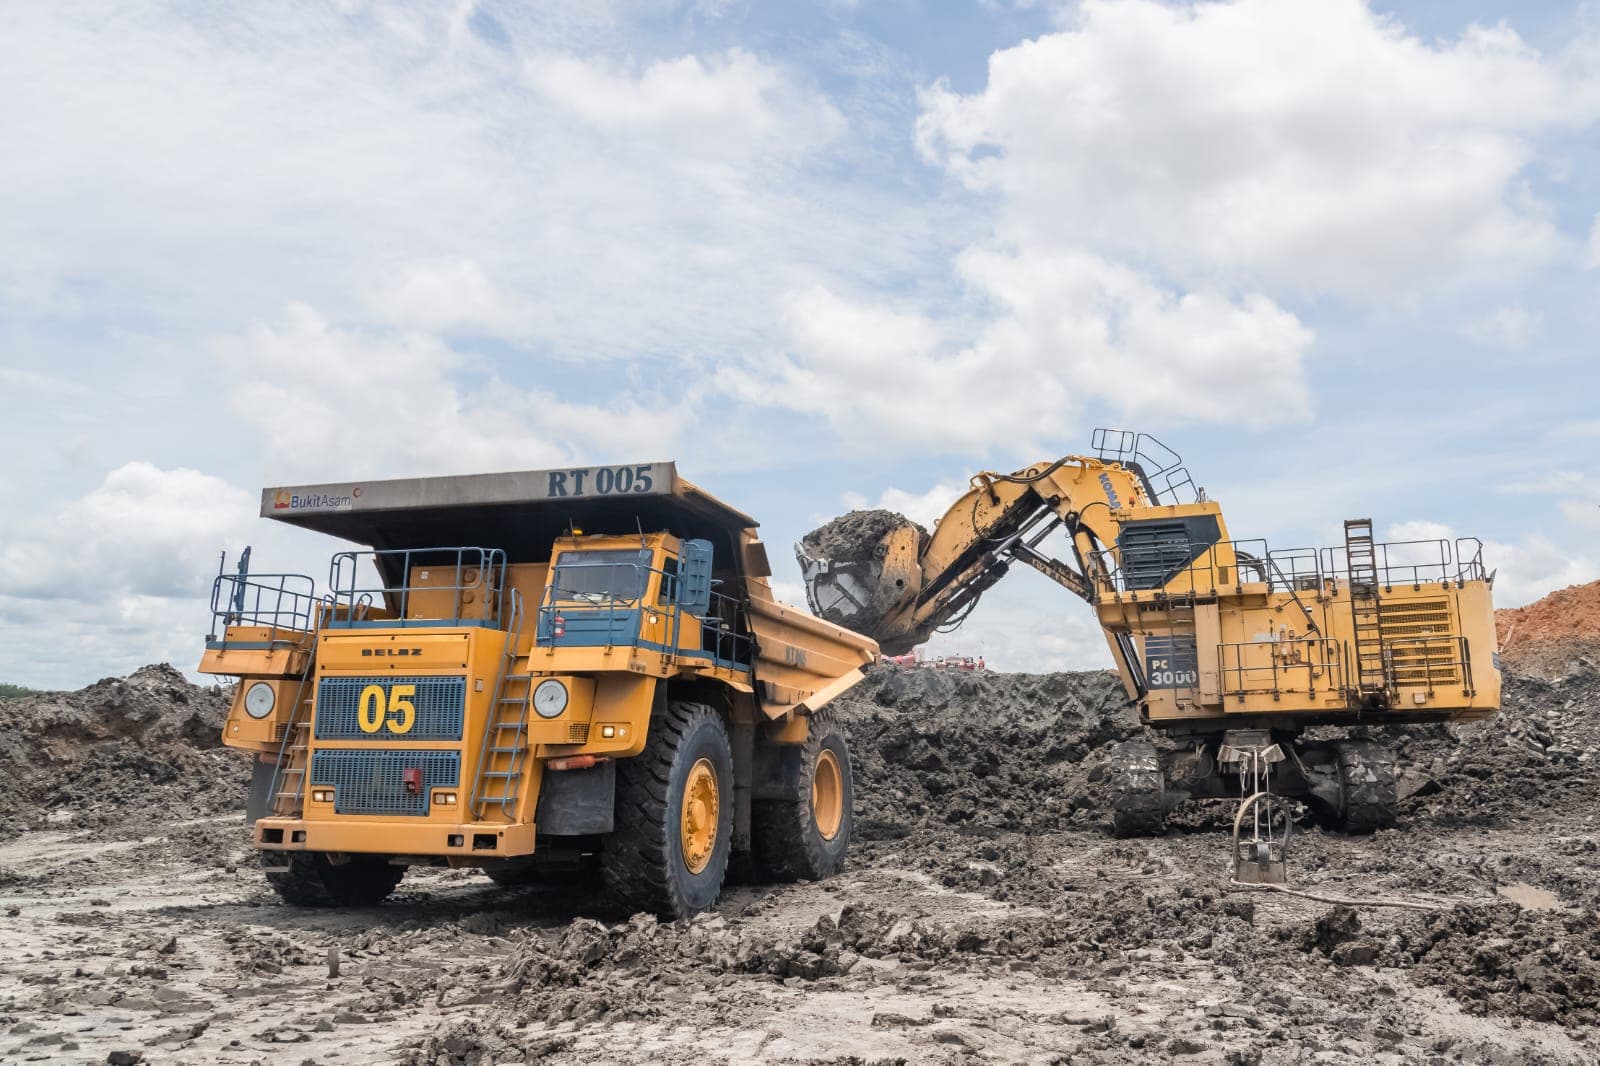
Jakarta, October 29, 2026 – PT Bukit Asam (Persero) Tbk (PTBA) announced its consolidated financial results for the nine-month period ended September 30, 2026 (9M2026) to the Indonesia Stock Exchange (IDX) and Financial Services Authority (OJK).
President Director Bambang Ismawan stated:
“Amid the evolving dynamics of the coal industry and operational challenges throughout 2026, PTBA successfully delivered solid financial performance growth in the first nine months of the year. This achievement was driven by a continued recovery in production during the third quarter, optimization of our sales mix to capitalize on stronger coal prices, and disciplined cost and operational management. Looking ahead, we remain committed to enhancing efficiency across our entire value chain, capturing opportunities in both domestic and export markets, and accelerating the development of logistics infrastructure to support sustainable business growth and create long-term value for all stakeholders.”
Key Highlights
- PTBA recorded a net profit of Rp4.41 trillion and EBITDA of Rp7.19 trillion, representing a net profit margin of 13% and an EBITDA margin of 20%, respectively.
- PTBA demonstrated a recovery in operational performance in 3Q26, marked by quarter-on-quarter (QoQ) increases in both production and sales volumes of 17% and 2%, respectively. In addition, the average selling price (ASP) increased by 7% QoQ and 18% year-on-year (YoY).
GUIDANCE FY26 PT BUKIT ASAM (PERSERO) TBK
- Production Volume: 49.55 million tonnes
- Sales Volume: 49.51 million tonnes
- Transportation Volume: 41.00 million tonnes
- Stripping Ratio: 5.63x
- Capital Expenditure: Rp3.64 trillion
Operational Performance
(in tonnes unless otherwise stated for stripping ratio)
|
|
9M26 a |
9M25 b |
%YoY (a:b) |
|
Production Volume |
34,409,648 |
35,895,510 |
96% |
|
Coal Transportation |
27,075,403 |
30,023,363 |
90% |
|
Sales Volume |
32,231,994 |
33,704,232 |
96% |
|
Domestic |
16,618,120 |
18,824,235 |
88% |
|
Export |
15,613,874 |
14,879,997 |
105% |
|
Stripping Ratio |
5.59 |
5.98 |
93% |
Financial Performance
(in million Rupiah unless otherwise stated for earnings per share)
|
Income Statement |
9M26 a |
9M25 b |
%YoY (a:b) |
|
Revenue |
35,201,385 |
31,330,296 |
112% |
|
Cost of Goods Sold |
27,935,167 |
27,764,355 |
101% |
|
Gross Profit |
7,266,218 |
3,565,941 |
204% |
|
Operating Profit |
5,113,743 |
1,595,842 |
320% |
|
Net profit for the year attributable to owners of the parent entity |
4,410,551 |
1,394,026 |
316% |
|
EBITDA |
7,191,854 |
3,556,870 |
202% |
|
Earnings per Share (EPS) |
383 |
121 |
317% |
|
|
|
|
|
|
Balance Sheet |
30 Sep 26 a |
31 Des 25 b |
%YoY (a:b) |
|
Total Assets |
51,550,907 |
43,917,063 |
117% |
|
Total Liabilities |
24,310,473 |
21,300,262 |
114% |
|
Total Equity |
27,240,434 |
22,616,801 |
120% |
|
Cash |
4,889,847 |
4,522,194 |
108% |
|
Bank Borrowings* |
4,211,352 |
3,227,525 |
130% |
*Includes back-to-back loan facilities secured by the placement of the Company's Export Proceeds (DHE).
9M2026 Financial Performance Analysis CONSOLIDATED STATEMENT OF PROFIT OR LOSS
Revenue and Average Selling Price
PT Bukit Asam Tbk (PTBA) recorded revenue of Rp35.20 trillion for the nine months ended September 2026, representing a 12% increase compared to the same period last year. Revenue growth was primarily driven by an 18% year-on-year (YoY) increase in the average selling price (ASP), supported by stronger global coal prices, as reflected in the 25% and 26% YoY increases in the Newcastle and ICI-3 indices, respectively.
The improvement in selling prices successfully offset a 4% YoY decline in sales volume. In terms of sales composition, the domestic market accounted for 52% of total sales volume, while exports contributed the remaining 48%. The Company’s five largest export destinations were Bangladesh, Vietnam, India, Cambodia, and Thailand.
Cost of Goods Sold and Operating Expenses
The Company’s cost of revenue stood at Rp27.94 trillion, increasing by approximately 1% compared to the same period last year. This increase was partly attributable to a 36% YoY rise in fuel prices, which affected operating costs associated with coal mining and transportation activities.
Nevertheless, the impact of higher fuel prices was partially offset by a lower stripping ratio, which declined from 5.98x to 5.59x, as well as decreases in coal production and transportation volumes of 4% and 10% YoY, respectively. These factors helped the Company contain its cost of revenue throughout the reporting period.
Meanwhile, operating expenses increased by Rp266.77 billion, or 13% YoY, in line with the development of operational activities throughout the current period.
Finance Income, Finance Costs, and Share in Net Profit of Associates and Joint Ventures The Company’s finance income increased by 16% YoY to Rp183.50 billion, primarily supported by higher placements in time deposits as part of its liquidity management strategy, including the placement of Export Proceeds (Devisa Hasil Ekspor/DHE) in accordance with the prevailing laws and regulations.
On the other hand, finance costs decreased by 45% YoY to Rp136.52 billion, reflecting lower interest expenses following the settlement of working capital credit facilities at the end of 2025.
In addition, the Company’s share of net profit of associates and joint ventures increased by 75% YoY to Rp581.31 billion.
Supported by revenue growth and effective cost management, the Company recorded profit for the period attributable to owners of the parent entity: Rp4.41 trillion.
CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
Total Assets
As of September 30, 2026, the Company’s total assets reached Rp51.55 trillion, representing a 17% increase compared to Rp43.92 trillion as of December 31, 2025. The increase was primarily driven by higher time deposits, an increase in trade receivables in line with stronger coal selling prices, and higher prepaid taxes related to Value Added Tax (VAT) refunds.
Total Liabilities and Equity
The Company’s total liabilities stood at Rp24.31 trillion as of September 30, 2026, increasing by 14% from Rp21.30 trillion as of December 31, 2025. The increase was mainly attributable to higher operating liabilities and additional bank borrowings to support the development of the Tanjung Enim–Kramasan Project.
Meanwhile, total equity increased by 20% to Rp27.24 trillion, compared to Rp22.62 trillion at the end of 2025. This growth was primarily driven by an increase in retained earnings, supported by the Company’s net profit generated during the reporting period.
CONSOLIDATED STATEMENTS OF CASH FLOWS
Cash Flows from Operating Activities
Net cash generated from operating activities increased by 9% YoY, from Rp4.20 trillion to Rp4.44 trillion for the nine months ended September 30, 2026. The increase was primarily attributable to improved profitability, along with lower payments to suppliers and reduced interest payments.
Cash Flows from Investing Activities
Net cash used in investing activities increased from Rp2.21 trillion in the corresponding period last year to Rp3.50 trillion for the nine months ended September 30, 2026. The increase in cash used in investing activities was primarily attributable to the placement of time deposits related to Export Proceeds (DHE).
Cash Flows from Financing Activities
Net cash used in financing activities decreased from Rp2.17 trillion in the corresponding period last year to Rp0.70 trillion for the nine months ended September 30, 2026. The reduction in net cash used in financing activities was primarily driven by lower dividend payments compared to the previous period, as well as increased proceeds from long-term borrowings to support the financing of the Tanjung Enim–Kramasan Project.
As closing statement, Eko Prayitno, Corporate Secretary Division Head, stated: