· News
Realizing Dream in Energy Sector
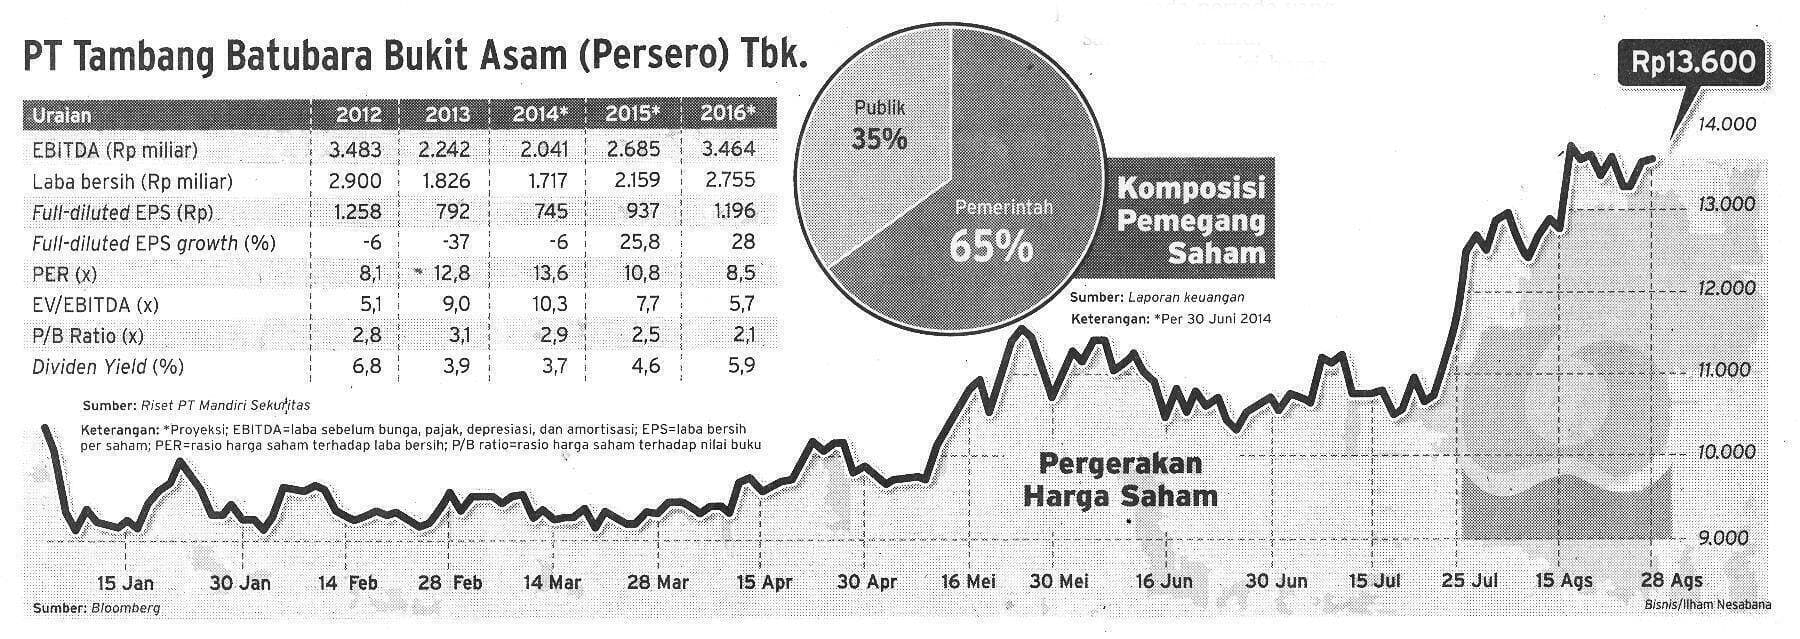
Image Source: PT Mandiri Sekuritas Research
Attractive business potential in electricity sector has lured PT Tambang Batubara Bukit Asam (Persero) Tbk. to dream of becoming world-class energy company. A dream which has existed since 1996 and has now started to become a reality.
Even before going public, PTBA has been mapping this business potential. The growth of electricity needs reaching more than 10% per year has become an opportunity as well as challenge for the company. At that time, coal reserves of Bukit Asam was about 7.3 billion tons in South Sumatera, West Sumatera, and Riau. The reserves had to be developed, one of which into electricity generator. PTBA then met with PT Perusahaan Listrik Negara (Persero) as the management of electricity in Indonesia. PLN explained the plan to develop Asean electricity line and PLTU Mulut Tambang. Joko Pramono, Secretary of PTBA, further explained the growth of electricity supply and infrastructure in Indonesia which could not accommodate demands, had prompted PTBA to take part in solving the problems. “It was In 2006 that the dream could be realized, but the dream had been there since 1996. We continuously strived to achieve those dreams of becoming world class energy company that are also environmental friendly,” he said to Bisnis on Thursday (28/8).
The company targeted to own electricity production capacity up to 5,500 MW by 2018. By end of 2017, PTBA was estimated to produce 1,500 megawatt electricity. Overall Bukit Asam had invested more than USD 3.79 billion, including those for the development of PLTU up to 2017 reaching 3500 MW. When all PLTU projects have been put into operation, the energy sector contribution is expected to reach 15-25% of the company’s net profit. This year, PTBA strives to complete some projects including PLTU Banjarsari 2x110MW in Lahat, South Sumatera. This PLTA is able to absorb 1.4 million tons of the company coal per year.
PTBA will also complete the first stage of PLTU Blank Tengah 2x620 MW, estimated on 2nd semester of 2014. The company will continue to the next stage: engineering, procurement, and construction estimated to take three years. PLTU Blanko Tengah is expected to operate on 2017. The Investment value of this project is approximately USD 1.6 billlion. For this project PTBA engaged the partnership with China Huan Dian (CHD), each with 45% and 55% ownership.
Other project, Mulut Tambang electricity generator with the capacity of 800-1,200 MW involving PTBA, PT PLN (persero), and TNB Malaysia is in progress.
Milawarma, CEO of PTBA is targeting electricity generator investment in two ASEAN countries, Myanmar and Vietnam. He estimated total investment fund required for 2 electricity generators in 2 countries reaches USD600 million.
The capacity that will be built in those two countries are each 2x100MW and investment required is approximately USD300 million.
PERFORMANCE OF THE FIRST SEMESTER 2014
During January to July 2014, PTBA gained net profit of IDR 1.16 zillion, increasing 33% from IDR 870 billion last year. The company revenue increased 18% to IDR 6.43 zillion. This performance was achieved by optimization of coal mining and sales operation. Coal sales increased 10.1% (8.83 million tons) from 8.74 million tons last year. The average coal sales price increased 17%. Arianto Kurniawan from PT Mandiri Securitas has released research analysis that PTBA profit was affected by coal sales price. In the first semester of 2014, the price of coal increased from IDR 621,792 per ton to IDR 726,776.
[PTBA targeted to be able to produce electricity up to 5,500 MW]
[PTBA projected investment in Myanmar and Vietnam]
While the coal price is unstable, PTBA stated to gain 26% EBITDA margin and 15% profit margin. Kurniawan said, ”However we find short term profit risk as coal price is still unstable”.
PT Onix Sekuritas analyst, Bagus Hananto, stated the company net profit increased 60 to 63% from the estimated.
He assumed operational expenditure affected estimated revenue 6% to become IDR 2 zillion from previously IDR 1.9 zillion. “PTBA has gained quite solid revenue during the first semester, estimated PER 12 times and EV/EBITDA 7.9 times. We suggest you to keep on buying PTBA share”, Hananto written on his research.
Bisnis Indonesia page 11, 29 August 2014
Written by Sukirno (sukirno@bisnis.co.id)