· Publication
Operational Performance Maintained, Bukit Asam (PTBA) Records Profit of Rp1.4 Trillion as of September 30, 2025
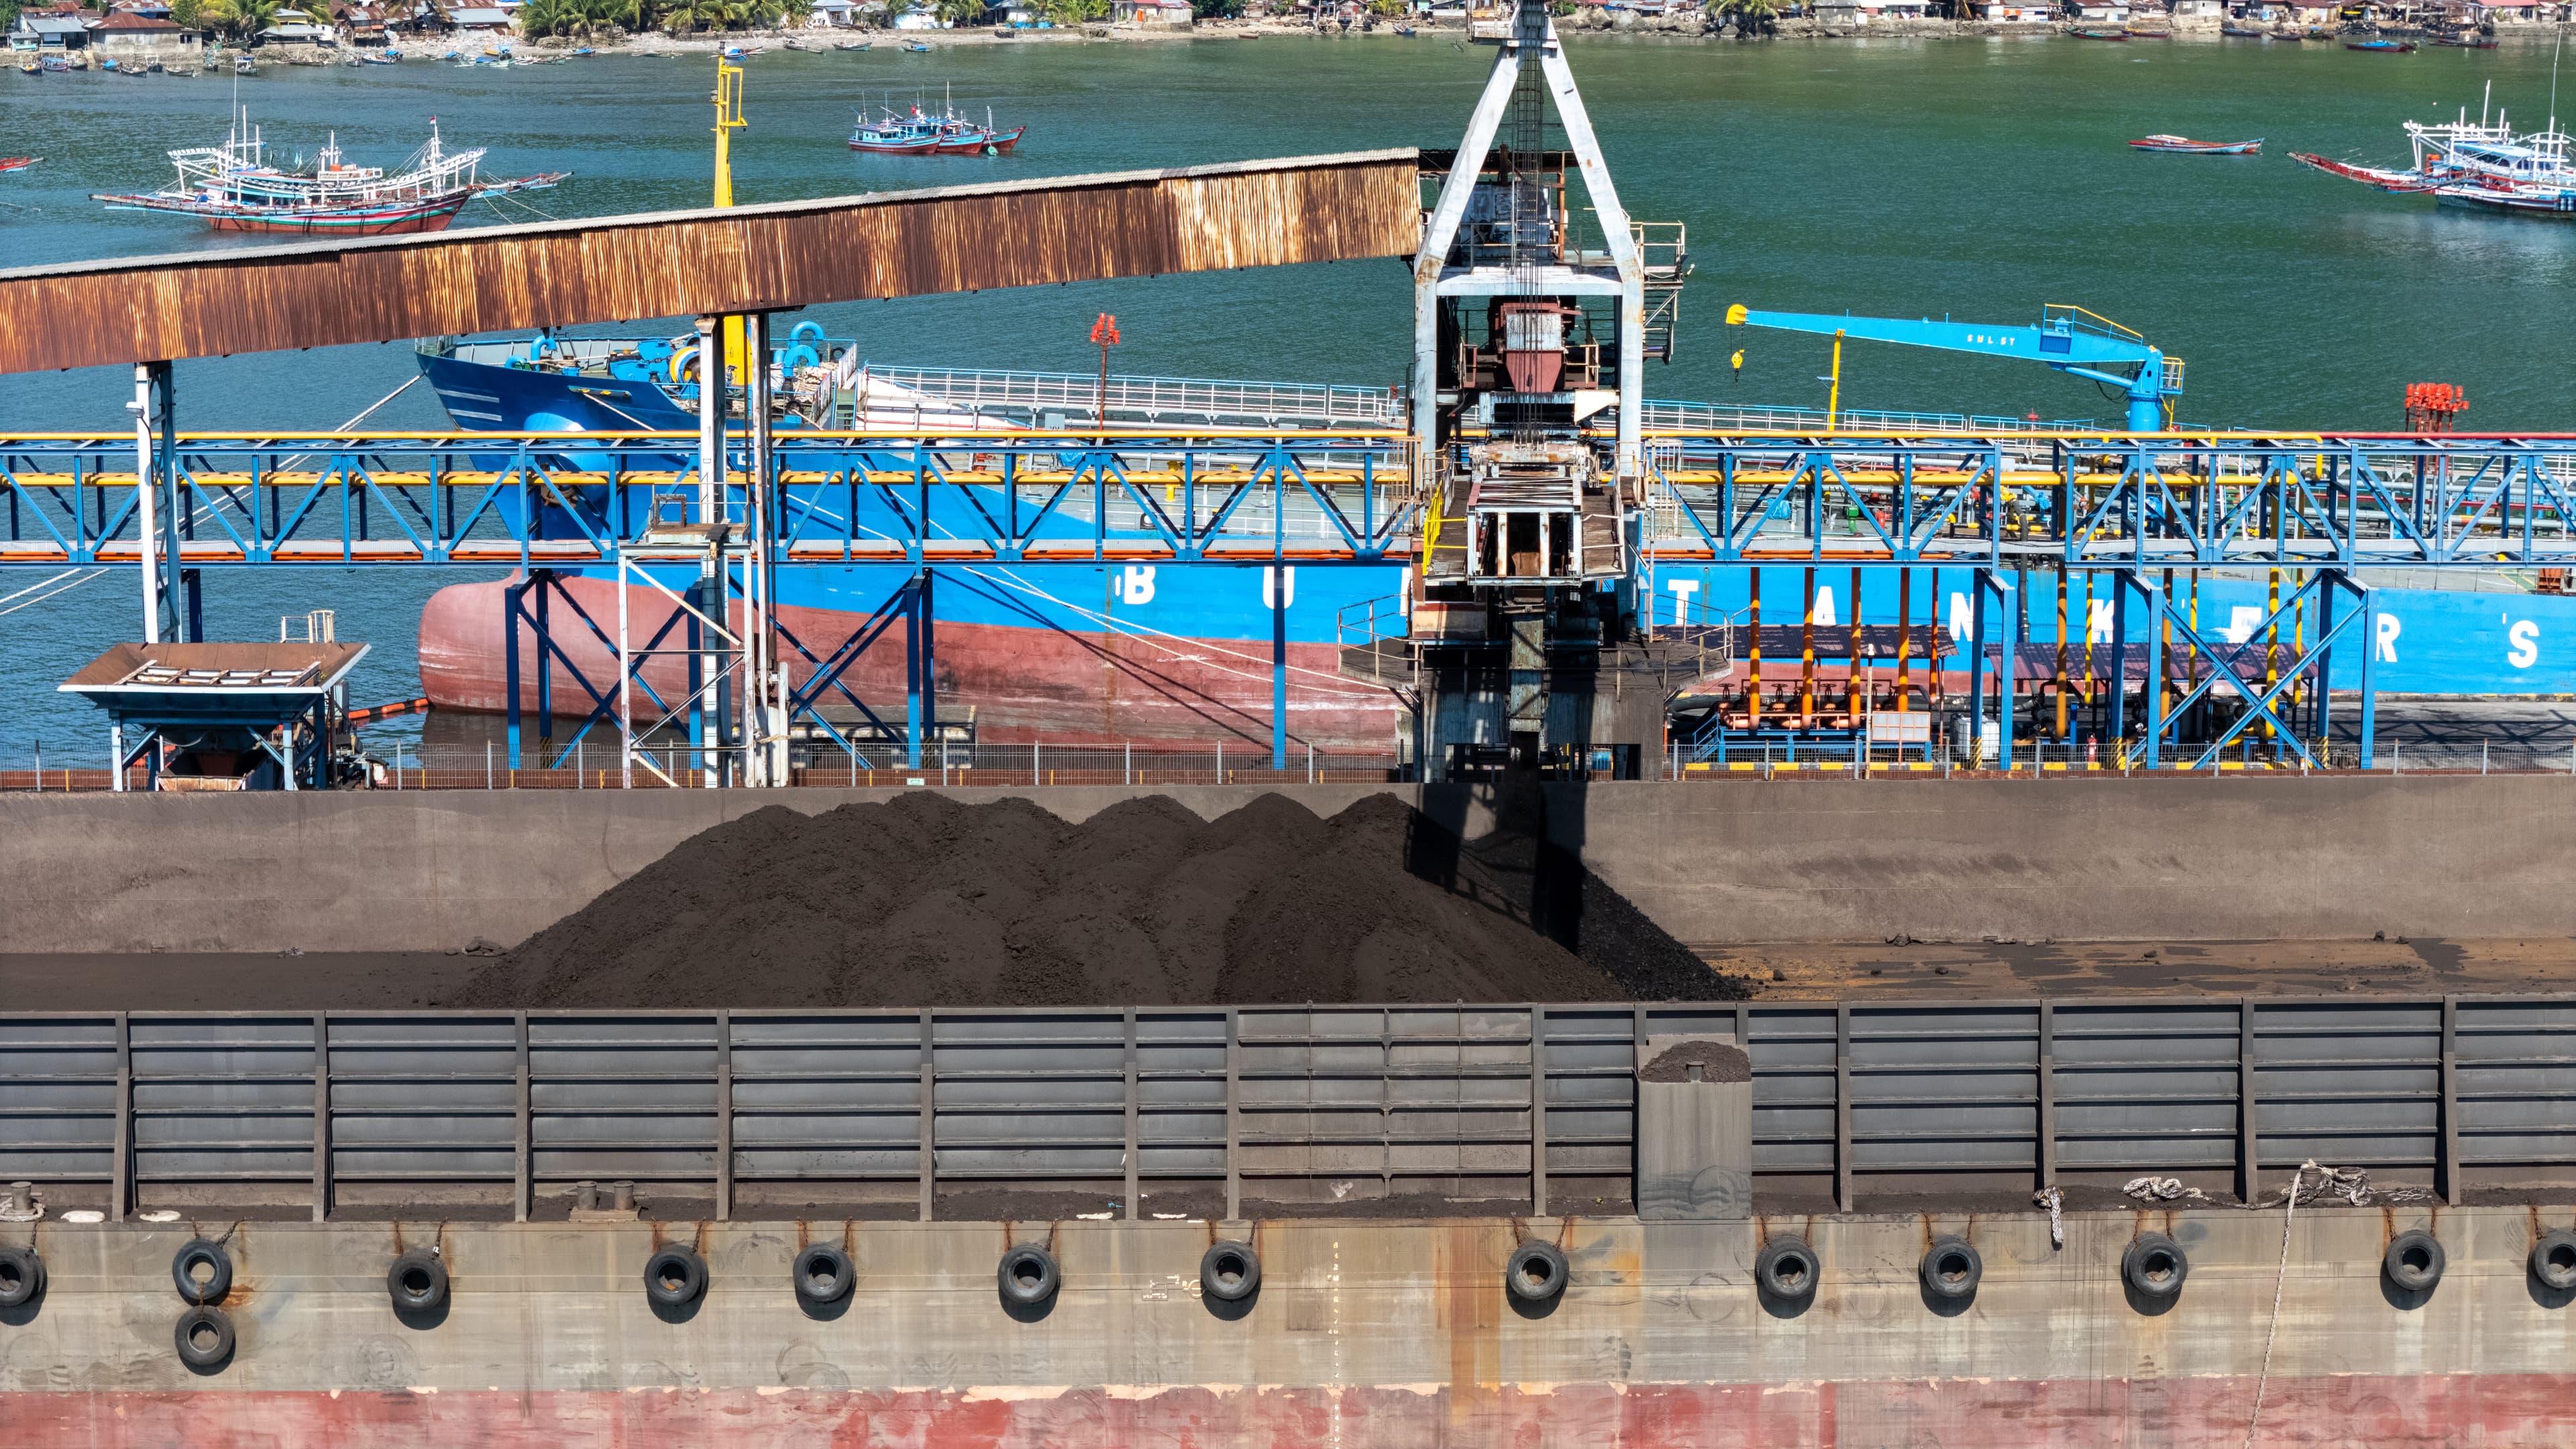
Operational Performance Maintained, Bukit Asam (PTBA) Records Profit of Rp1.4 Trillion as of September 30, 2025
Jakarta, October 30, 2025 – PT Bukit Asam Tbk (PTBA) announced its consolidated financial performance for the nine-month period ending September 30, 2025 (9M25) to IDX/OJK.
President Director of PTBA, Arsal Ismail, stated, "Amid the continued decline in global coal prices throughout 2025, PT Bukit Asam Tbk (PTBA) managed to maintain solid operational performance and profitability through cost efficiency improvements and optimization of the domestic market portfolio. This is reflected in the positive growth in production and sales volumes, as well as capex realization that supports operational sustainability and strategic logistics projects."
Highlights
- PTBA recorded a net profit of Rp1.4 Trillion and EBITDA of Rp3.6 Trillion, with an EBITDA margin of 11%.
- Operational performance remained solid with production growth of 9% and sales growth of 8% YoY. However, the average selling price (ASP) declined by 6%, in line with falling coal prices (NCI down 22%, ICI-3 down 16% YoY).
- Capital expenditure realization reached 41% of the annual target, or Rp3.0 Trillion as of Q3 2025.
FY25 Guidance
- Production Volume : 50.05 Million tons
- Sales Volume : 50.09 Million tons
- Coal Transportation : 43.25 Million tons
- Stripping Ratio : 6.49x
- Capital Expenditure : Rp7.2 Trillion
Operational Performance
(in tons unless otherwise stated for stripping ratio)
|
9M24 |
9M25 |
% Changes |
|
|
Production Volume |
32,970,174 |
35,895,510 |
+9% |
|
Sales Volume |
31,277,526 |
33,704,232 |
+8% |
|
Domestic |
16,982,759 |
18,824,235 |
+11% |
|
Export |
14,294,767 |
14,879,997 |
+4% |
|
Coal Transportation |
27,828,707 |
30,023,363 |
+8% |
|
Stripping Ratio |
6.02 |
5.98 |
|
Financial Performance
(in Million Rupiah unless otherwise stated for earnings per share)
|
Income Statement |
9M24 |
9M25 |
% Changes |
|
Revenue |
30,655,933 |
31,330,296 |
+2% |
|
Cost of Goods Sold |
25,047,684 |
27,764,355 |
+11% |
|
Gross Profit |
5,608,249 |
3,565,941 |
-36% |
|
Operating Profit |
3,919,848 |
1,595,842 |
-59% |
|
EBITDA |
5,653,761 |
3,556,870 |
-37% |
|
Earnings per Share (EPS) |
281 |
121 |
-57% |
|
Financial Position |
31 Des 24 |
30 Sep 25 |
% Changes |
|
Total Assets |
41,785,576 |
42,836,755 |
+3% |
|
Total Liabilities |
19,141,764 |
22,063,478 |
+15% |
|
Total Equity |
22,643,812 |
20,773,277 |
-8% |
|
Cash |
4,132,858 |
4,005,385 |
-3% |
|
Interest-bearing Debt* |
1,397,680 |
3,401,960 |
+143% |
|
Capital Expenditure |
2,348,332 |
2,985,280 |
+27% |
*Not included least liabilities (PSAK 73)
FINANCIAL PERFORMANCE ANALYSIS FOR 9M–2025
CONSOLIDATED STATEMENTS OF PROFIT OR LOSS
Revenue and Average Selling Price
Revenue reached Rp31.3 Trillion, up 2% YoY. Despite an 8% increase in sales volume, the average selling price declined 6% YoY due to falling coal indices (Newcastle Index -22%, ICI-3 -16%). Domestic sales accounted for 56%, while exports made up 44%. Top export destinations: Bangladesh, India, Philippines, Vietnam, and South Korea.
Cost of Goods Sold and Operating Expenses
COGS rose 11% YoY to Rp27.8 Trillion , driven by higher production (+9%) and transport volumes (+8%), despite a lower stripping ratio (5.98x vs. 6.02x). The removal of FAME subsidies and B40 mandate increased fuel prices (+8% YoY), impacting mining and rail transport costs. General and administrative expenses rose 4% YoY, while selling and marketing expenses fell 1%.
Finance Income, Finance Costs, and Share in Net Profit of Associates and Joint Ventures
Finance income dropped 14% YoY to Rp157.6 Billion. Finance costs rose 23% YoY to Rp247.9 Billion due to higher level of bank loan. Share in net profit of associates and joint ventures rose 14% YoY to Rp333.1 Billion.
Net profit for the period attributable to owners of the parent entity: Rp1.4 Trillion
CONSOLIDATED STATEMENTS OF FINANCIAL POSITION
Total Assets
As of September 2025, total assets stood at Rp42.8 Trillion, an increase of 3% from Rp41.8 Trillion at the end of 2024. Cash and cash equivalents amounted to Rp4.0 Trillion, slightly down 3% from Rp4.1 Trillion at year-end 2024.
Total Liabilities and Equity
Total liabilities rose from Rp19.1 Trillion (end of Dec 2024) to Rp22.1 Trillion as of September 2025. Meanwhile, equity decreased from Rp22.6 Trillion to Rp20.8 Trillion. As a result, total liabilities and equity reached Rp42.8 Trillion, up 3% from Rp41.8 Trillion at year-end 2024.
CONSOLIDATED STATEMENTS OF CASH FLOWS
Cash Flows from Operating Activities
Net cash provided by operating activities decreased from Rp4.4 Trillion to Rp4.2 Trillion, or a 4% decline year-on-year (YoY). This decrease was mainly due to higher payments to suppliers and employees influenced by the increase in fuel prices.
Cash Flows from Investing Activities
Net cash used in investing activities increased from Rp0.8 Trillion in the previous period to Rp2.2 Trillion as of September 2025. The increase was primarily driven by the addition of fixed assets and productive plants, which rose from Rp1.4 Trillion in the previous period to Rp2.4 Trillion at the end of September 2025.
Cash Flows from Financing Activities
Net cash used in financing activities decreased from Rp3.1 Trillion in the previous period to Rp2.2 Trillion. This decrease was mainly attributable to lower dividend payments this year and a reduction in bank loan repayments. In the current year, the Company distributed dividends amounting to Rp3.9 Trillion.
Capital Expenditures
Capital expenditures as of September 2025 reached Rp3.0 Trillion, with the majority allocated for the development of the Tanjung Enim-Kramasan transportation projects.
As closing statement, Eko Prayitno, Corporate Secretary Division Head, stated, "PTBA consistently applies internal cost leadership to achieve optimal performance. Price recovery is expected to positively impact the company alongside marketing and operational strategies. Despite global market challenges and coal price corrections, PTBA continues to deliver positive performance. Moving forward, the company will enhance cost efficiency, improve performance, and expand its sustainable business portfolio."
This article was published on Bisnis.com